Company Anatomy | Memo & Viewpoints. Research checked 9 October 2026, 4:02 pm IST. This memo covers the 8 October transaction and closing prices. Counterparty details below are attributed to reporting of BSE disclosures.
ITC’s reported ₹9,437 crore block deal has put a large ownership transfer alongside an already difficult earnings recovery. The useful question is whether the price now compensates investors for the cash flows they can reasonably expect under the changed cigarette-tax regime.
The transaction itself does not answer that question. It does, however, give investors a reason to revisit the assumptions behind their valuation rather than anchor to an earlier share price.
What was reported
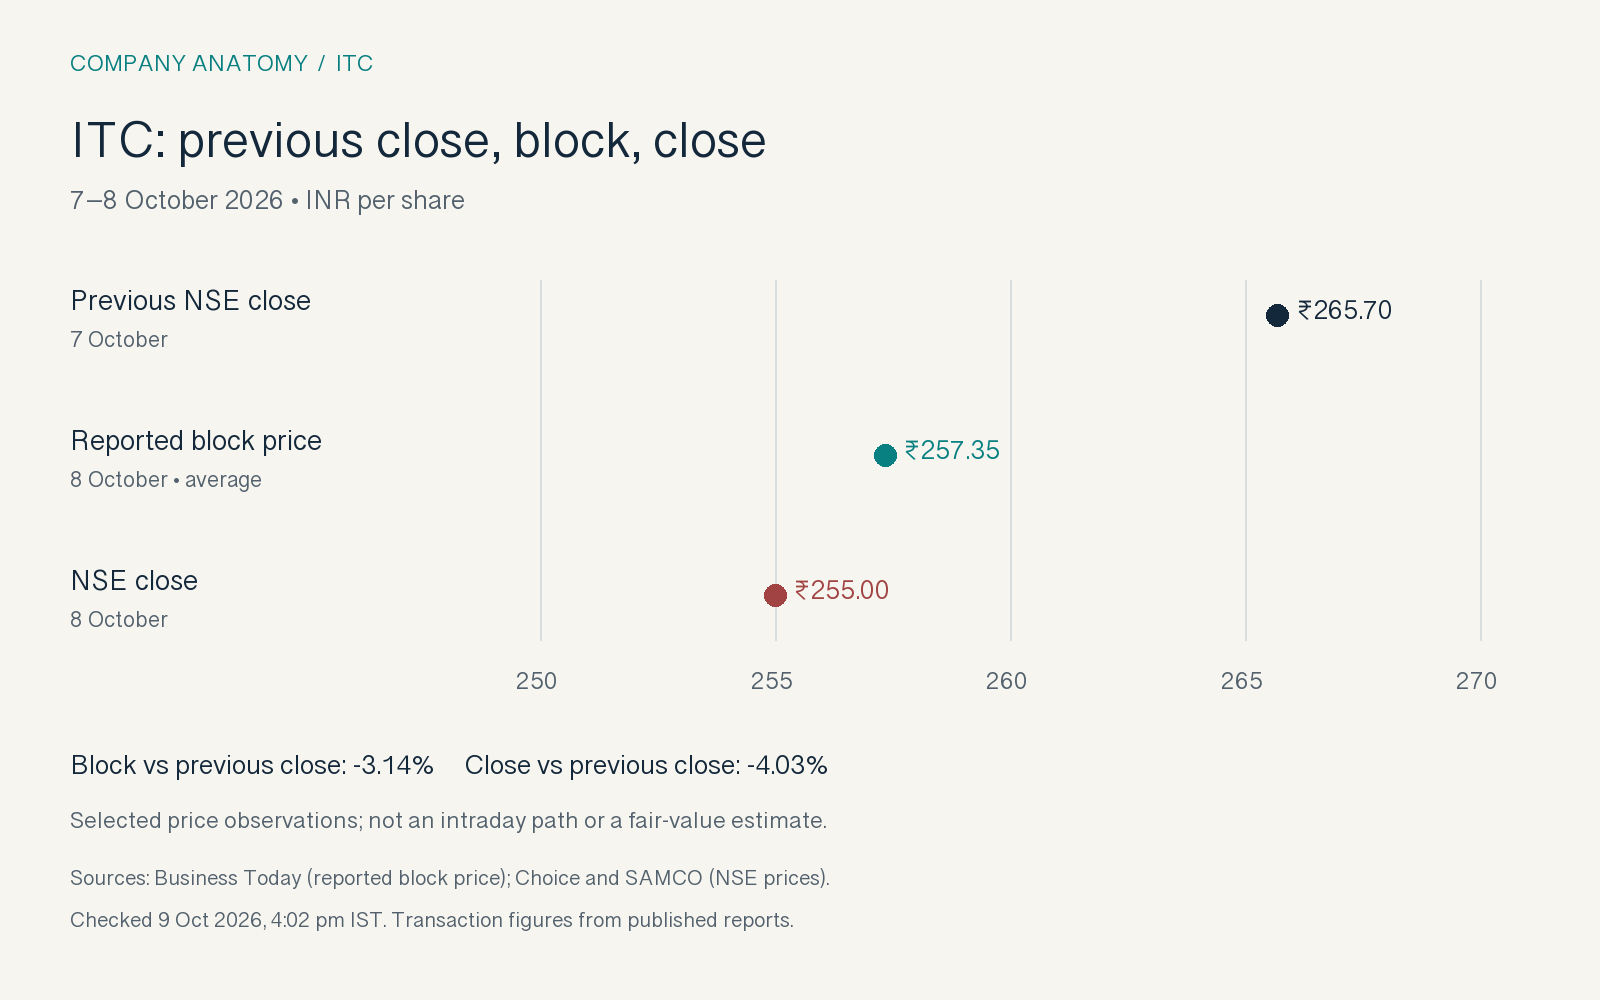
Business Today reported that 36,66,95,297 shares changed hands on 8 October at an average ₹257.35, valuing the transaction at ₹9,436.90 crore. That is approximately 36.67 crore shares, or about 2.9% of ITC’s equity. Other reports rounded the quantity to 36.66 crore and the price to ₹257.
ITC’s NSE closing price was ₹255, down ₹10.70, or 4.03%, from ₹265.70. Choice’s historical-price table and SAMCO’s post-market quote corroborate those figures. Using the more precise reported deal price, the block cleared approximately 3.14% below the previous NSE close. The closing price finished approximately 0.91% below that block price.
These comparisons describe traded prices. They do not establish intrinsic value or isolate how much of the day’s decline was caused by the transaction.
What the later counterparty reports show
Post-market reporting has moved beyond the earlier “likely seller” description. Moneycontrol, citing BSE block-deal data, identified GQG Partners Emerging Markets Equity Fund A Series of GQG Partners Series LLC as selling approximately 36.5 crore shares for ₹9,395.44 crore. Alliance Witan also sold approximately 16.11 lakh shares for ₹41.46 crore. Together, the reported proceeds reconcile to the roughly ₹9,437 crore headline.
The report names 14 institutional buyers. Fidelity Advisor Overseas Fund bought 13.4 crore shares and ICICI Prudential Mutual Fund bought approximately 9.4 crore. SBI Mutual Fund and Nippon India Mutual Fund were among the other buyers. Business Standard independently reported the GQG-linked sale and Alliance Witan’s participation. We could not retrieve the underlying BSE report directly, so these details remain explicitly attributed.
A separate earlier GQG disclosure reported by Moneycontrol covered approximately 3.97 crore shares sold between 28 May 2025 and 5 October 2026. That period ends before this block deal.
The buyer list establishes reported ownership transfers, not the seller’s motivation or every GQG-linked entity’s remaining holding. A complete exit and the exhaustion of future selling pressure are not established here. Rebalancing, liquidity needs or a revised investment view remain possible explanations rather than verified motives.
Ownership changes; operating economics need a separate test
A secondary-market sale transfers existing shares and payment between investors. On the transaction as reported, ITC receives no fresh capital, issues no new shares and makes no payment to the seller. The ₹9,437 crore headline is therefore not a reduction in ITC’s cash balance or an operating loss.
That distinction should not become reassurance that the business faces no pressure. ITC’s own Q1 FY2027 release, for the quarter ended 30 June 2026, reported standalone net revenue down 14% year on year, EBITDA down 28% and profit after tax down 27%. FMCG–Others revenue grew 12%, with segment PBIT up 21%.
The company described staggered cigarette-price increases and portfolio changes intended to limit migration to illicit trade after the tax increase. Its FY2026 results release dates the tax change to 1 February 2026 and warns that gross revenue and excise-duty comparisons are affected by the new structure.
For valuation, this makes net realisations, cigarette volumes and segment profits more useful than a headline gross-revenue growth number. The commercial challenge is how much tax can be passed through without losing too much profitable demand.
The Company Anatomy view
A lower purchase price can improve prospective returns if sustainable earnings remain intact. It can also accompany a justified reduction in earnings expectations. Both possibilities deserve space in the investment case.
The constructive case is that ITC’s pricing and product changes stabilise cigarette economics while FMCG–Others builds a larger profit contribution. The risk is that legal cigarette volumes or margins remain under pressure for longer, leaving diversification unable to offset the earnings shortfall quickly enough.
A disciplined valuation should therefore stress-test slower recovery, weaker cigarette profitability and the cash required for investment. Historical earnings multiples and past dividends need to be evaluated against future earning capacity. Neither a large institutional buyer nor a negotiated block price removes that work.
Our ITC research report provides the broader company-analysis context. The Yoga Bar capital-allocation memo is a complementary lens: acquisitions should ultimately be judged by incremental profits and returns on the capital committed.
What would change the assessment?
Three developments matter next:
- Subsequent ownership disclosures would clarify remaining holdings and whether further selling follows. The reported buyer list does not, by itself, establish fair value.
- Sustained stabilisation in cigarette volumes, net realisations and segment profitability would strengthen the recovery case. Continued deterioration despite pricing action would weaken it.
- FMCG profit growth converting into cash and satisfactory returns on incremental investment would improve the diversification argument. Revenue growth without comparable economic returns would be less persuasive.
The block deal belongs in the ownership record. The investment decision still rests on sustainable cash generation, the price paid for it and the possibility that recovery takes longer than expected.
This article is for information and education, not personalised investment advice.
Disclosure: The author holds ITC shares as a long-term investment and may have positions in ITC derivatives.
Regulatory information
This page provides general information about Company Anatomy and the disclosure principles applied to its research. Every dated research report must also be read with its own disclosures, assumptions, risks and source notes.
Research Analyst information
| Name | Aditya Siddharth Mehta |
|---|---|
| Capacity | SEBI-registered Research Analyst — individual registration |
| SEBI registration number | INH000029768 |
| SEBI validity from | 20 August 2026 — Perpetual |
| BSE enlistment number | 7462 |
| Business name | Company Anatomy |
| Telephone | +91 7021135925 |
| Email and grievance contact | adi2001me@gmail.com |
| Correspondence address | Aditya Villa, Daksha Niwas, S.T. Road, Chembur, Mumbai, Maharashtra 400071 |
Business activities and service scope
Company Anatomy publishes independent equity research and educational material concerning Indian listed companies. Research may include business analysis, financial estimates, valuation work, risks and analyst judgement. The website does not provide portfolio management, trade execution, custody, banking, legal, tax or personalised financial-planning services.
Independent and completely free public research
All Company Anatomy research and reports are independent and completely free to read and download. There is no subscription charge, purchase condition or obligation to open a brokerage account or trade. Free public access is a core value of Company Anatomy. Research opinions are intended to reflect analysis and evidence rather than a reader’s transactions.
Merely reading or downloading publicly available research does not by itself create a personalised investment-advisory engagement or an agreement for a separately arranged service. It does not waive investor protections or remove applicable Research Analyst obligations. Whether a particular relationship constitutes a client relationship depends on the actual arrangements and applicable law, including direct or indirect economic benefits; it cannot be settled by calling a report “free”.
Reports are not an offer, invitation or solicitation to buy or sell any security or to enter into a transaction. Where a report contains a recommendation, rating or target price, it remains research subject to applicable requirements; it is not personalised investment advice. Do not use a report as the sole basis for an investment decision.
General nature of research
Research and recommendations are general and are not tailored to an individual reader’s objectives, financial situation, risk tolerance or needs. General website information is not a personalised investment recommendation or a solicitation of an offer to buy or sell a security. This distinction does not exclude the Research Analyst’s applicable regulatory duties. Investors should make an independent assessment and obtain professional advice appropriate to their circumstances.
Sources, estimates and changes
Information is obtained from sources believed to be reliable, with preference for company filings, exchange disclosures and other primary material. Accuracy, adequacy and completeness are not guaranteed. Information may be incomplete or condensed. Forecasts, valuations, target prices and scenarios are estimates rather than facts. Opinions and estimates are the Research Analyst’s judgement as of the stated date and may change without notice.
Ownership, financial interests and material conflicts
Each research report or public recommendation must state, as applicable, whether the Research Analyst, associates or relatives have a financial interest in the subject company; actual or beneficial ownership of one per cent or more of its securities at the end of the month immediately preceding publication; or another material conflict of interest. Aditya Siddharth Mehta has confirmed that there is no business conflict of interest as of 17 September 2026. This business-conflict declaration is not a declaration that the analyst, associates or relatives have no security holdings or issuer relationships. Because holdings and circumstances can change, this general page does not make a permanent “no conflict” representation. The dated report-specific disclosure governs.
Compensation and other relationships
Each research report must disclose applicable compensation received from the subject company during the preceding twelve months, including compensation for investment-banking, merchant-banking, brokerage or other products and services; compensation or benefits connected with the research; whether the subject company was a client during the applicable period; and participation in managing or co-managing a public offering. No blanket statement is made on this page because the disclosure must be current for the subject company and report date.
Other report-specific declarations
- Whether the Research Analyst serves as an officer, director or employee of the subject company.
- Whether the Research Analyst has engaged in market-making activity in the subject company’s securities.
- Relevant associates, business relationships and any fact that could affect independence or objectivity.
- The valuation method and material risks that may prevent achievement of a stated target price.
- Any material disciplinary history, regulatory action, litigation, inspection or investigation required to be disclosed.
If a required report-specific declaration is absent or unclear, do not rely on the recommendation until clarification is obtained from the Research Analyst.
Use of artificial intelligence
Company Anatomy uses artificial intelligence to improve readability and writing, assist valuation calculations and run simulations. The extent and material role of AI in a particular report should be read with that report’s methods and source notes. The Research Analyst remains responsible for the research, human review, accuracy controls, security, confidentiality, integrity and regulatory compliance, regardless of the extent of AI use. AI can produce incorrect text, calculations or assumptions. Readers should cross-check material figures against original filings and source documents, examine assumptions and periodically consult a SEBI-registered investment adviser about their own financial circumstances. These precautions do not transfer the analyst’s regulatory responsibilities to the reader.
Valuation, forecasts and simulation limitations
Valuation models and simulations are conditional analytical tools. Outputs depend on input quality, assumptions, correlations, distributions and model design; they can omit risks and produce materially different results when assumptions change. A simulated frequency is not an observed probability of future investment success. Model values and target prices are not guarantees, promises of returns or precise forecasts. Review the valuation date, horizon, scenarios, sensitivity analysis and downside risks. Historical or simulated performance does not establish future performance.
Market risk and performance
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
Past performance is not an indicator of future performance. Prices and returns may be volatile, and an investor may lose part or all of the capital invested. Registration granted by SEBI, enlistment with BSE and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Distribution, report versions and corrections
Research is intended for lawful access and use. It is not directed to a person or jurisdiction where distribution or use would breach applicable law or require a registration that the Research Analyst does not hold. Free access is not a representation of authorisation outside India. When sharing a report link, retain its date, author, qualifications and disclosures; do not present extracts or simulations as guaranteed returns. A downloaded copy reflects its stated publication date. Check the original report page for subsequent revisions and contact the Research Analyst about a suspected error.
Website, third-party links and liability
The website and its content are provided for information on an “as is” and “as available” basis. Links to third-party websites are provided for convenience and do not constitute endorsement. To the extent permitted by applicable law, Company Anatomy is not responsible for decisions made solely in reliance on general website content or for loss arising from third-party content, interruptions or technical errors. Nothing on this page excludes duties or liability that cannot lawfully be excluded.
Grievances and dispute resolution
First raise a concern directly with Company Anatomy using adi2001me@gmail.com. If the response is unsatisfactory, use SEBI SCORES. Eligible unresolved disputes may be taken to SMART ODR in accordance with the applicable process. See the Grievance Redressal, Investor Charter and Investor Complaints pages.
Regulatory sources
- SEBI Master Circular for Research Analysts, 6 February 2026
- SEBI Investor Charter for Research Analysts, 2 June 2025
Last reviewed: 17 September 2026. This page should be updated when the applicable regulatory framework or the Research Analyst’s material circumstances change.