SEBI Registered Research Analyst · Registration No. INH000029768
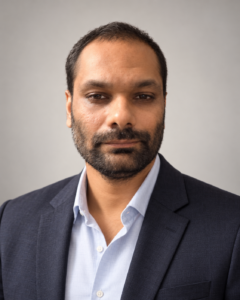
I am Aditya Siddharth Mehta, a SEBI Registered Research Analyst and the publisher of Company Anatomy, an independent equity-research publication focused on Indian listed companies.
My approach to investing is built around a simple idea:
A business cannot be understood through finance alone.
Companies are complex systems shaped by customers, competitors, incentives, capital allocation, technology, psychology, regulation, industry structure and sometimes sheer human behaviour. Understanding them therefore requires drawing from more than one discipline.
Multidisciplinary Value Investing
My investment philosophy has been strongly influenced by Warren Buffett and Charlie Munger, particularly their emphasis on thinking like a business owner, understanding intrinsic value, protecting against permanent capital loss and building a latticework of mental models from multiple disciplines.
But Company Anatomy is not an attempt to mechanically reproduce anyone else’s investment style.
The objective is to take the underlying principles and use them as a foundation for independent research.
Traditional fundamental analysis asks questions such as:
- What does the company earn?
- What is its balance sheet?
- What is the stock worth?
Multidisciplinary analysis goes further.
It asks:
Why does the business earn what it earns?
What forces determine whether those economics improve or deteriorate?
Why do customers behave the way they do?
What incentives influence management, competitors, distributors and shareholders?
What assumptions does the current market price require to be true?
What could permanently impair the business or the investment?
The purpose of using multiple mental models is not intellectual decoration. It is to reduce the probability of seeing a business through a single, incomplete lens.
A latticework rather than a formula
No single valuation model can adequately describe every business.
I therefore draw selectively from disciplines including:
Economics — incentives, supply and demand, competitive structure, economies of scale and pricing power.
Accounting — cash generation, working capital, return on invested capital, balance-sheet strength and the difference between reported earnings and economic reality.
Psychology — social proof, incentives, loss aversion, commitment, overconfidence and other behavioural forces affecting management, customers and investors.
Probability — thinking in ranges of outcomes rather than pretending the future can be forecast precisely.
Business strategy — competitive advantage, customer behaviour, distribution, industry structure and barriers to entry.
Technology — understanding how technological change can strengthen, weaken or completely alter an existing business model.
Systems thinking and engineering — identifying bottlenecks, feedback loops, constraints, operating leverage and second-order effects.
History — studying previous cycles, competitive battles and capital-allocation decisions to establish useful base rates.
Each model is incomplete.
Together, they can produce a more useful approximation of reality.
Understand the business before valuing the stock
A share is an ownership interest in a real operating business.
Research therefore starts with the economic machine underneath the ticker symbol.
I want to understand:
How does the company actually make money?
Why do customers choose it?
Where does its bargaining power come from?
What limits competitors?
How much capital must be reinvested to grow?
What return does the business earn on incremental capital?
Where does the cash ultimately go?
How does management allocate that cash?
And, most importantly:
What has to remain true for the economics of this business to endure?
Only after building that understanding does valuation become particularly useful.
Long-term orientation
Company Anatomy is deliberately oriented toward multi-year business economics rather than short-term market prediction.
Quarterly results matter when they provide evidence about the underlying business.
They matter much less when they are simply noise around a longer-term economic trajectory.
I am therefore generally more interested in changes in competitive position, customer behaviour, reinvestment opportunity, unit economics, capital allocation and industry structure than in trying to predict the next quarter’s earnings per share.
The distinction matters.
A stock price can move dramatically while the underlying value of the business changes very little.
Conversely, a business can slowly deteriorate while its share price continues rising.
The research process attempts to separate the two.
Price is not value
A wonderful company can be a poor investment at an unreasonable price.
An ordinary company can occasionally become an interesting investment at a sufficiently attractive price.
Business quality and investment attractiveness are therefore related, but they are not identical questions.
Rather than asking only:
“What should this stock trade at?”
Company Anatomy often asks:
“What assumptions about the future are already embedded in today’s price?”
This reverse-valuation perspective can expose situations where expectations have become unusually optimistic or pessimistic.
Valuation is therefore treated as a range of possible outcomes based on explicit assumptions—not as a precise prediction of the future.
Inversion: how could I be wrong?
Finding evidence supporting an investment thesis is relatively easy.
The harder and more valuable exercise is searching for evidence that could destroy it.
Every serious research process should therefore contain an adversarial component.
What would make this thesis fail?
Which assumption carries the greatest weight?
What is the strongest argument on the other side?
What am I assuming because everyone else assumes it?
Where could incentives distort the information I am receiving?
What could cause permanent impairment of capital?
What evidence would cause me to change my view?
This process of inversion is central to Company Anatomy’s research philosophy.
The goal is not to defend an opinion.
The goal is to get closer to reality.
Temperament matters
Investing is unusual because intelligence alone is insufficient.
Markets continuously expose investors to fear, greed, envy, social proof, authority bias, recency bias and the temptation to act simply because everyone else is acting.
A multidisciplinary approach therefore applies behavioural analysis not only to companies and markets, but also to the analyst.
Before concluding that the market is wrong, an investor should first ask whether they might be wrong.
Intellectual independence requires intellectual humility.
I try to distinguish clearly between:
Facts — what the available evidence establishes.
Estimates — calculations dependent on assumptions.
Judgement — my interpretation of what those facts and estimates mean.
That distinction is fundamental to the research published on Company Anatomy.
An operator’s perspective
My professional experience has extended beyond securities research into digital business, marketing, entrepreneurship, retail and technology-led automation.
That experience has influenced how I analyse companies.
Businesses on spreadsheets can appear cleaner than businesses in reality.
In the real world, execution depends on customers, employees, systems, incentives, distribution, working capital, operational constraints and countless small decisions.
I therefore try to understand not merely whether a company’s strategy sounds attractive, but whether the underlying operating system can realistically produce the outcomes investors expect.
I hold an MSc in Management from the University of Sheffield.
Why Company Anatomy exists
The name Company Anatomy describes the purpose of the publication.
The objective is to take businesses apart intellectually and understand the organs underneath the headline numbers:
the revenue engine,
the customer proposition,
the competitive system,
the economics,
the balance sheet,
management incentives,
capital allocation,
valuation,
risks,
and the assumptions connecting them.
The ambition is not to produce more information.
Markets already contain enormous quantities of information.
The ambition is to produce better understanding.
Research should help a reader move from:
What happened?
to
Why did it happen?
to
What determines what happens next?
That is the standard Company Anatomy aims to pursue.
Independent thinking, continuously updated
No research report is permanently correct.
Businesses evolve. Industries change. Competitors respond. Technology advances. Management changes. New evidence appears.
A research view should therefore remain a hypothesis rather than become an identity.
When important facts change, the analysis should change with them.
The aim is not consistency of opinion.
It is consistency of process.
Observe carefully. Think independently. Value conservatively. Search for disconfirming evidence. Protect against permanent loss. Update when the facts change.
That is the philosophy behind Company Anatomy.
About the publication
Company Anatomy publishes independent research on Indian listed companies, including:
- Detailed company research
- Industry and sector analysis
- Valuation and reverse-valuation frameworks
- Analytical memos and viewpoints
- Educational research material
Research published on Company Anatomy is general in nature and does not constitute personalised investment advice. Readers should consider the assumptions, risks, valuation framework, disclosures and source notes accompanying each research report before making investment decisions.
Registration details
| Name | Aditya Siddharth Mehta |
|---|---|
| SEBI Registration No. | INH000029768 |
| Telephone | +91 7021135925 |
| adi2001me@gmail.com | |
| Registered / Correspondence Address | Aditya Villa, Daksha Niwas, S.T. Road, Chembur, Mumbai, Maharashtra 400071 |
Full contact, grievance-redressal and regulatory information is available through the Investor Information section of this website.