Swan Defence and Heavy Industries reported ₹524.78 crore of consolidated profit for the six months ended September 2026. Its order book reached approximately ₹6,500 crore. Both numbers demand a closer reading: the profit includes a ₹563.15 crore tax-provision writeback, while much of the shipbuilding work will be delivered several years from now.
Our assessment is that the October 12 results strengthen the evidence of a commercial restart, but do not yet establish repeatable shipbuilding returns. The investment case depends on delivery, customer funding and the cash left after completing contracts. Company results and presentation
What generated the reported profit
Fact: Consolidated operating revenue increased from ₹39.99 crore to ₹99.46 crore, approximately 149%. Yet the half-year pretax loss widened from ₹3.48 crore to ₹38.37 crore. Other income contributed ₹68.41 crore to total income of ₹167.87 crore. Investors should therefore avoid reading total income as shipyard sales. Consolidated results, PDF page 9
The large profit arrived through the tax line. Note (e) explains that provisions inherited from Triumph Offshore were reassessed against the merged accounts and consolidated tax position. A ₹56,315.17 lakh provision, or ₹563.1517 crore, was considered unnecessary and written back. This is an earlier-years tax-provision writeback. Deferred tax appears separately in the results. Amalgamation and tax notes, PDF page 12
Calculation: A pretax loss of ₹38.3722 crore, plus the ₹563.1517 crore writeback, less ₹0.0001 crore of deferred tax, produces reported profit of ₹524.7794 crore. Removing this specific credit leaves a loss of approximately ₹38.37 crore. That calculation isolates one accounting effect; it is not a comprehensive estimate of normal earnings.
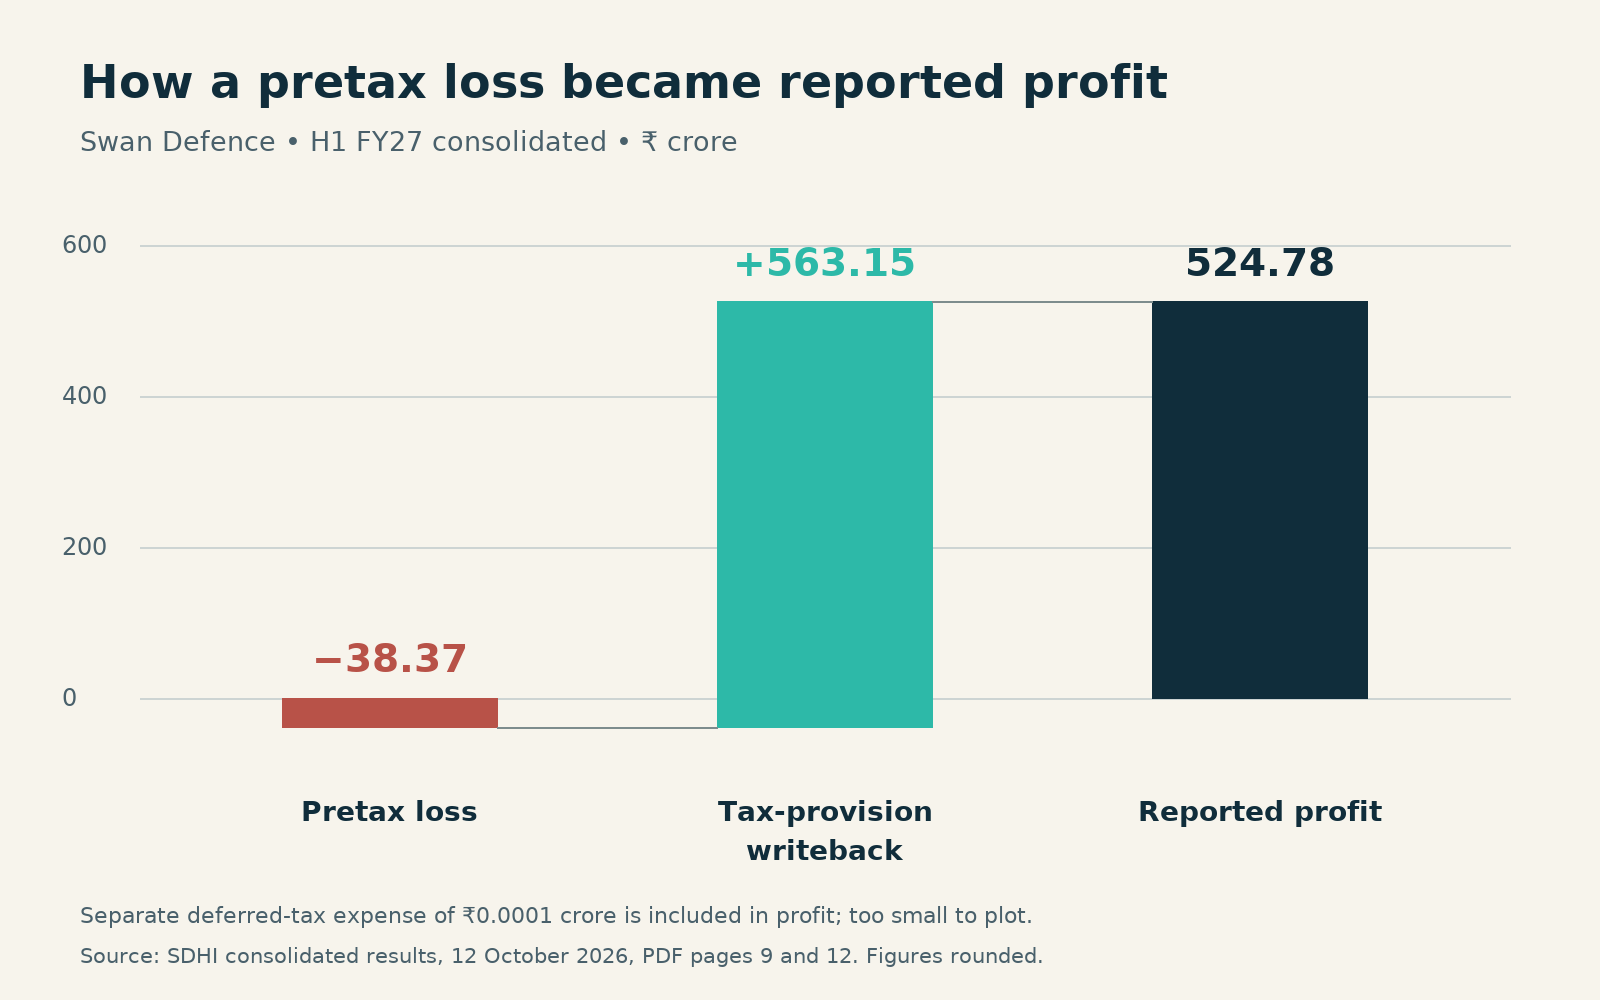
The accounting treatment does not by itself imply anything improper. It does mean that this period’s profit and earnings per share are poor starting points for a recurring earnings multiple. Our Yoga Bar acquisition memo discussed a different mechanism, the remeasurement of an existing stake. The shared analytical discipline is to separate an accounting gain from repeatable operating earnings; the two accounting treatments should not be conflated.
The comparison now includes Triumph Offshore
The amalgamation became effective on September 17, 2026, with an appointed date of April 1, 2024. It used pooling-of-interests accounting, and the comparative periods were restated. These are consolidated figures for the listed company, including its associate Conceptia; they are not Swan Corp’s group results. Results notes (d), (g) and (h)
This matters when comparing the release with older presentations. Investors need the restated series, rather than mixing today’s enlarged accounting perimeter with previously published numbers. The notes also describe loan netting and amalgamation-related equity adjustments. Those balance-sheet changes should not be counted as cash earned from delivering vessels.
The order book has a delivery calendar
Management calls the approximately ₹6,500 crore backlog firm orders and says it provides visibility through FY31. It comprises six chemical tankers for Rederiet Stenersen, four ammonia dual-fuel bulk carriers for Energy ONE, four Svitzer harbour tugs and a Royal Navy of Oman training ship. Tanker deliveries begin in FY29; bulk carriers from FY30. Tug deliveries are scheduled from early 2028. Options for additional tankers and tugs should remain outside an investor’s firm-order assumptions until exercised. Presentation, printed slide 13
That timetable explains why dividing the backlog by current revenue is unhelpful. Half-year revenue describes an early execution stage; backlog combines different projects and future years. Contract value also says nothing by itself about profit margins, escalation clauses, cancellation protection or how much cash must be advanced before the next customer payment.
The reviewed release does not establish a contract-by-contract schedule of customer advances, milestone receipts or peak working-capital requirements. Those are important unanswered questions. An advance can fund steel and equipment, but it also creates a delivery obligation. Cash received today cannot all be treated as distributable surplus.
Physical capacity needs operating proof
The company describes a 662-metre by 65-metre dry dock and fabrication capacity of approximately 164,000 tonnes a year. It completed seven repair and refit projects during the half and started steel cutting for five L&T barge unloaders. These are tangible signs of activity. The presentation also targets more than 550 additional hires by March 2027. Company release and presentation, slides 2 and 11
Our inference is that repair work can help rebuild utilisation, supplier relationships and execution routines while larger vessels move through production. But installed capacity does not establish annual output, delivery reliability or return on capital. Sophisticated propulsion systems, design approvals, equipment lead times and workforce productivity can become constraints before dock dimensions do.
Cash generation needs a reconciliation
The consolidated cash-flow statement shows ₹447.44 crore after tax in its operating section. That figure deserves care: the trade-and-other-receivables movement alone contributes ₹426.80 crore. The statement also records ₹428.43 crore invested in shares of a related party and ₹66.43 crore across property purchases and increased capital work in progress. Cash and equivalents fell by ₹96.65 crore during the half. Cash-flow statement, PDF page 11
These figures do not establish recurring cash generation from current shipbuilding contracts. The statement contains presentation inconsistencies: the subtotal within operating activities is labelled investing cash flow, and its starting pretax loss differs from the profit-and-loss statement. However, the latter difference is exactly offset by the associate adjustment, leaving the same ₹37.62 crore loss before the associate contribution. These deserve clarification, but do not by themselves change the cash-flow subtotal. The more important economic question is whether the large working-capital release can recur.
Capital allocation also extends beyond cranes and docks. Related-party investments need to be assessed alongside spending on the yard, with their purpose, recoverability and eventual benefit to common shareholders understood.
Financing support changes the calculation
Management presents a ₹1,150 crore NaBFID term loan with an initial coupon of 8.85% and a 5.85% effective coupon after applicable interest support. Brownfield expansion has in-principle approval, with assistance subject to scheme conditions. These are useful financing levers; eligibility and receipt timing still belong in the cash model. Presentation, slides 8–9
The September balance sheet also includes approximately ₹1,594.97 crore of preference share capital pending allotment, also present in the restated March balance sheet. This is not fresh cash raised during the half. Its economic rights must be understood before translating enterprise value into value for ordinary shareholders. Treating every rupee labelled equity as equivalent to listed common equity would miss that distinction. Balance sheet, PDF page 10
What would strengthen or weaken the case
The constructive case is credible: export customers have placed orders, repair activity is producing delivery evidence, and an existing large yard could benefit from rising utilisation. Customer-funded milestones and timely incentives could reduce the capital needed for growth.
The countercase is a long production cycle that absorbs cash before margins become visible. Delivery delays, cost overruns, insufficient advances or repeated additional funding would weaken the economics even if announced orders keep rising.
A useful valuation therefore models delivery schedules, contract margins, cash taxes, working capital, capital spending and financing obligations under several execution scenarios. It then accounts for debt, genuinely available cash, preference rights and other claims before arriving at common-equity value. Neither headline price-to-earnings nor a fixed multiple of backlog answers those questions.
For now, the evidence to watch is straightforward: on-time milestones, disclosed customer funding, operating profitability without the tax credit, and a reconciled cash-flow bridge. Swan Defence has secured work. Shareholder returns will depend on the capital and cash required to complete it.
Disclosure: The author confirms that he, his associates and relatives have no holdings in Swan Defence and no compensation or dealings with the company.
Regulatory information
This page provides general information about Company Anatomy and the disclosure principles applied to its research. Every dated research report must also be read with its own disclosures, assumptions, risks and source notes.
Research Analyst information
| Name | Aditya Siddharth Mehta |
|---|---|
| Capacity | SEBI-registered Research Analyst — individual registration |
| SEBI registration number | INH000029768 |
| SEBI validity from | 20 August 2026 — Perpetual |
| BSE enlistment number | 7462 |
| Business name | Company Anatomy |
| Telephone | +91 7021135925 |
| Email and grievance contact | adi2001me@gmail.com |
| Correspondence address | Aditya Villa, Daksha Niwas, S.T. Road, Chembur, Mumbai, Maharashtra 400071 |
Business activities and service scope
Company Anatomy publishes independent equity research and educational material concerning Indian listed companies. Research may include business analysis, financial estimates, valuation work, risks and analyst judgement. The website does not provide portfolio management, trade execution, custody, banking, legal, tax or personalised financial-planning services.
Independent and completely free public research
All Company Anatomy research and reports are independent and completely free to read and download. There is no subscription charge, purchase condition or obligation to open a brokerage account or trade. Free public access is a core value of Company Anatomy. Research opinions are intended to reflect analysis and evidence rather than a reader’s transactions.
Merely reading or downloading publicly available research does not by itself create a personalised investment-advisory engagement or an agreement for a separately arranged service. It does not waive investor protections or remove applicable Research Analyst obligations. Whether a particular relationship constitutes a client relationship depends on the actual arrangements and applicable law, including direct or indirect economic benefits; it cannot be settled by calling a report “free”.
Reports are not an offer, invitation or solicitation to buy or sell any security or to enter into a transaction. Where a report contains a recommendation, rating or target price, it remains research subject to applicable requirements; it is not personalised investment advice. Do not use a report as the sole basis for an investment decision.
General nature of research
Research and recommendations are general and are not tailored to an individual reader’s objectives, financial situation, risk tolerance or needs. General website information is not a personalised investment recommendation or a solicitation of an offer to buy or sell a security. This distinction does not exclude the Research Analyst’s applicable regulatory duties. Investors should make an independent assessment and obtain professional advice appropriate to their circumstances.
Sources, estimates and changes
Information is obtained from sources believed to be reliable, with preference for company filings, exchange disclosures and other primary material. Accuracy, adequacy and completeness are not guaranteed. Information may be incomplete or condensed. Forecasts, valuations, target prices and scenarios are estimates rather than facts. Opinions and estimates are the Research Analyst’s judgement as of the stated date and may change without notice.
Ownership, financial interests and material conflicts
Each research report or public recommendation must state, as applicable, whether the Research Analyst, associates or relatives have a financial interest in the subject company; actual or beneficial ownership of one per cent or more of its securities at the end of the month immediately preceding publication; or another material conflict of interest. Aditya Siddharth Mehta has confirmed that there is no business conflict of interest as of 17 September 2026. This business-conflict declaration is not a declaration that the analyst, associates or relatives have no security holdings or issuer relationships. Because holdings and circumstances can change, this general page does not make a permanent “no conflict” representation. The dated report-specific disclosure governs.
Compensation and other relationships
Each research report must disclose applicable compensation received from the subject company during the preceding twelve months, including compensation for investment-banking, merchant-banking, brokerage or other products and services; compensation or benefits connected with the research; whether the subject company was a client during the applicable period; and participation in managing or co-managing a public offering. No blanket statement is made on this page because the disclosure must be current for the subject company and report date.
Other report-specific declarations
- Whether the Research Analyst serves as an officer, director or employee of the subject company.
- Whether the Research Analyst has engaged in market-making activity in the subject company’s securities.
- Relevant associates, business relationships and any fact that could affect independence or objectivity.
- The valuation method and material risks that may prevent achievement of a stated target price.
- Any material disciplinary history, regulatory action, litigation, inspection or investigation required to be disclosed.
If a required report-specific declaration is absent or unclear, do not rely on the recommendation until clarification is obtained from the Research Analyst.
Use of artificial intelligence
Company Anatomy uses artificial intelligence to improve readability and writing, assist valuation calculations and run simulations. The extent and material role of AI in a particular report should be read with that report’s methods and source notes. The Research Analyst remains responsible for the research, human review, accuracy controls, security, confidentiality, integrity and regulatory compliance, regardless of the extent of AI use. AI can produce incorrect text, calculations or assumptions. Readers should cross-check material figures against original filings and source documents, examine assumptions and periodically consult a SEBI-registered investment adviser about their own financial circumstances. These precautions do not transfer the analyst’s regulatory responsibilities to the reader.
Valuation, forecasts and simulation limitations
Valuation models and simulations are conditional analytical tools. Outputs depend on input quality, assumptions, correlations, distributions and model design; they can omit risks and produce materially different results when assumptions change. A simulated frequency is not an observed probability of future investment success. Model values and target prices are not guarantees, promises of returns or precise forecasts. Review the valuation date, horizon, scenarios, sensitivity analysis and downside risks. Historical or simulated performance does not establish future performance.
Market risk and performance
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
Past performance is not an indicator of future performance. Prices and returns may be volatile, and an investor may lose part or all of the capital invested. Registration granted by SEBI, enlistment with BSE and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Distribution, report versions and corrections
Research is intended for lawful access and use. It is not directed to a person or jurisdiction where distribution or use would breach applicable law or require a registration that the Research Analyst does not hold. Free access is not a representation of authorisation outside India. When sharing a report link, retain its date, author, qualifications and disclosures; do not present extracts or simulations as guaranteed returns. A downloaded copy reflects its stated publication date. Check the original report page for subsequent revisions and contact the Research Analyst about a suspected error.
Website, third-party links and liability
The website and its content are provided for information on an “as is” and “as available” basis. Links to third-party websites are provided for convenience and do not constitute endorsement. To the extent permitted by applicable law, Company Anatomy is not responsible for decisions made solely in reliance on general website content or for loss arising from third-party content, interruptions or technical errors. Nothing on this page excludes duties or liability that cannot lawfully be excluded.
Grievances and dispute resolution
First raise a concern directly with Company Anatomy using adi2001me@gmail.com. If the response is unsatisfactory, use SEBI SCORES. Eligible unresolved disputes may be taken to SMART ODR in accordance with the applicable process. See the Grievance Redressal, Investor Charter and Investor Complaints pages.
Regulatory sources
- SEBI Master Circular for Research Analysts, 6 February 2026
- SEBI Investor Charter for Research Analysts, 2 June 2025
Last reviewed: 17 September 2026. This page should be updated when the applicable regulatory framework or the Research Analyst’s material circumstances change.